


 CDN NEWS |
 US NEWS


By Maureen McCall
By Maureen McCall
Canada’s Energy Sector Built for Global Capital
On September 15TH, at Prime Minister Mark Carney’s first Canada Investment Summit, nearly $500 billion in new investment commitments were announced by the end of the day, according to the Prime Minister’s Office.
It is a number that has created optimism all week.
Carney has focused on leveraging the strengths of the Canadian economy to catalyze $1 trillion of new investment and create growth and opportunity. Of the $500 bn in new commitments, Canada’s pension funds, insurers, and institutional investors committed nearly $100 bn in new capital to Canadian assets.
Which projects and which parts of the economy will see those investments first?
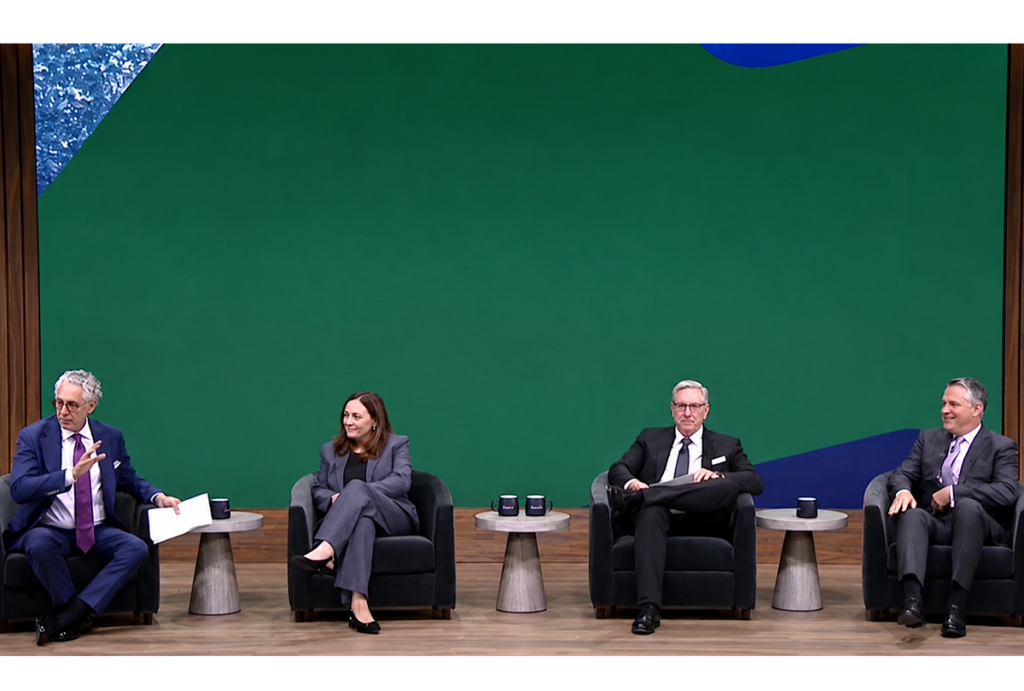
At the Investment Summit, a panel of energy industry leaders discussed the needs and attractions of the Canadian energy sector in a session titled “Canada’s Energy Sector Built for Global Capital”.
They discussed the investment potential of $300 bn in upstream oil and gas, clean energy, and electrical power and utilities alone. That is a sizeable chunk of the incoming commitments of $500 bn and a bit less than one third of the $1 tn target.
Panel Moderator Peter Tertzakian, the Founder of Studio Energy and author of fourteen books on the energy industry, is well known for his writing examining the economic, environmental and geopolitical pressures on the global energy sector. He was joined by Nicolle Butcher, President & Chief Executive Officer, Ontario Power Generation, Rich Kruger, President & Chief Executive Officer, Suncor, and François Poirier, President & Chief Executive Officer, TC Energy.
But first, we should take a moment to quantify some of the value and investments that the companies represented by the panellists have created. François Poirier spoke about TC Energy’s $75 billion investment in North America, with $25 billion projected for gas alone. Nicole Butcher detailed Ontario Power Generation’s $12.8 billion nuclear refurbishment and plans for SMRs, and Rich Kruger emphasized Canada’s competitive position in oil and gas, noting a 31% reduction in carbon intensity over 15 years. Not only were the panellists focused on the importance of secure, reliable energy, but they also advocated for responsibly produced energy.
What the World Needs to Feed A Voracious Appetite for Energy
Peter Tertzakian began by commenting on Mark Carney’s oft-repeated maxim about the strength of the Canadian energy industry – “Canada has what the world wants” and suggested that it could more accurately be said that “Canada Offers What the World Needs.”
Suncor President & CEO Rich Kruger, who has worked in the energy industry for more than 40 years, provided important context to the discussion, clarifying that nearly 60% of the world’s energy needs today are met by oil and gas. Projections suggest that demand will stay at or near that level well into the future, according to Kruger, and he noted that oil and gas are depletable resources, so new investments will be needed just to meet demand. Of the top 10 countries that hold roughly 90% of the world’s remaining resources, Canada is arguably number three on the list, and has enormous resources with essentially no exploration risk. Finding oil in Canada in the old sense is not hard. Developing it is a bit of a bigger challenge. Since Canada is a democratic country which respects the sanctity of contract, the rule of law, and has skilled labour, Canada has the ingredients for long-term success in the oil and gas world.
“We fundamentally produce global commodities,” Kruger said. “So we have to be globally competitive for capital, and that takes being able to plan, develop, and get projects approved and executed. It takes fiscal packages that provide the right balance of risk and reward. And to contrast the past, we’ve been out of balance the last decade or more. But I see the federal government, in collaboration with the provincial governments, is bringing that back into balance, where once again I think we can attract capital. So the accelerated depreciation and capital cost allowances that were announced today, and streamlined, more efficient project approvals…those are all part of ensuring global competitiveness in the oil and gas world.”
Francois Poirier, President & CEO of TC Energy (TCE), spoke about developments for their infrastructure for moving energy. He pointed out that more energy flows back and forth across the Canada-U.S. border than any other border in the world. TCE is forecasting 51 billion cubic feet(BCF) a day of incremental natural gas demand in North America between now and 2035. That’s equivalent to the entirety of Europe’s natural gas demand. Eight BCF of that 51 BCF of demand growth will come from Canada.
“The beauty about Canada is we have a resource that is incredibly cost competitive,” Poirier said. “The resource at current consumption levels at very competitive costs will last 50 or 100 years. So our challenge and our opportunity, given that we produce 185 percent of our annual energy consumption in Canada, is ‘what can we do to bring energy affordability and reliability to the rest of the world’? For much of the history of TC Energy, it’s been about North America. In the last 10 years, there’s been a huge ramp-up in LNG on the Gulf Coast, and recently LNG on the West Coast. We are talking about the strategic positioning of Canada, both East and West, as it relates to serving the rest of the world, particularly our allies, with that affordable, reliable, secure, trusted energy that the world needs.”
The geopolitical developments in the Strait of Hormuz and in the South China Sea have brought a focus on Canada, which has a transportation path for LNG that is free of any conflict to the highest growth market for LNG over the next decade – Asia. The United States has not developed LNG facilities off the West Coast in states like Washington, Oregon, and California, where permitting challenges abound. It’s created a tremendous opportunity for Canada to increase its exports. Prime Minister Carney wants to grow LNG exports to 50 megatons per year from the 14 megatons that it is at now.
Nicolle Butcher, President & CEO, Ontario Power Generation (OPG), described OPG’s diverse portfolio – providing about 50% of the power in the province of Ontario, possessing a significant nuclear fleet, owning most of the hydro in the province and a third of the natural gas fleet, as well as having solar and biomass, and battery storage projects currently under construction. Having just completed a 10-year refurbishment project on one of their nuclear plants, they are moving on to SMRs and are building the first SMR in the G7.
Regulatory – Right-sizing with a Global Context
Panellists generally agreed that although previously Canada, from a regulatory standpoint, had complex, overlapping regulations, and long timelines to “get a project to the finish line”, the changes are now coming quickly. Establishing the major projects office, announcements of changes to the required impact assessments, the collaboration between provinces and the federal government around an aligned vision of what a project can become are resonating with energy companies. Kruger acknowledged that “For a capital allocator and investor, that presents opportunities today that I wouldn’t have considered a few short years ago. We’re dusting off project inventories, we’re updating them, we’re looking at how we would approach the market. It’s a very different environment today than the past.”
Poirier said the changes proposed at the Summit and the changes already implemented were going to have a huge impact on how companies make their capital allocation decisions. Some Canadian companies over the last five or 10 years have been allocating most of their discretionary capital for growth outside Canada- in the United States and Mexico, for example. A big contributor to that practice was uncertainty – the enemy of investment. Panellists agreed that the current administration has been listening to the private sector to a degree not seen in quite a long time, and the consultations have been reflected in the legislation that is proposed to be tabled on regulatory reform. Panellists expect the legislation to be tabled in the next few weeks.
“But I want to emphasize that one year versus what’s been two to two and a half years for reviews at this point does not mean that any of the quality of the review and the rigour of the review will be compromised,” Poirier said. “There’s a lot of redundancy. There’s a lot of overlap between provincial and federal jurisdictions. There are a lot of processes that can be done concurrently to make a review successful in one year and still have the rigour that citizens expect. There’s much more certainty, and the policy support that’s there has already had a major influence in where we are allocating our development dollars.”
Nicole Butcher added that the most important near-term investment for companies is actually in the supply chain. She advised that when OPG looks at what they need to build out their second, third, and fourth SMR units, and other expansion work, they need to actually start building manufacturing facilities in the next 18 to 24 months, so that they can hit long lead times for the early 2030s. This involves a significant investment in manufacturing capability and expansion. Peter Tertzakian agreed and noticed that there has been little discussion of the probably another $100 bn that is required in upstream investment to fill new pipelines, particularly the project for the West Coast oil pipeline. There has been little talk not only about the upstream energy capital required to fill the pipes, but also about capital needed for data centers, referring to all the natural gas drilling and nuclear expenditures that are required to power them.
Maureen McCall is an energy professional who writes on issues affecting the energy industry.
Share This:
SETTING OFF ALARM BELLS: Carney’s EU Deal Threatens Alberta, Energy, & Sovereignty – 170,000 Reasons to Reject Canada’s EU “Associate Membership” – The Nemeth Report