CDN NEWS |
 US NEWS


By Maureen McCall
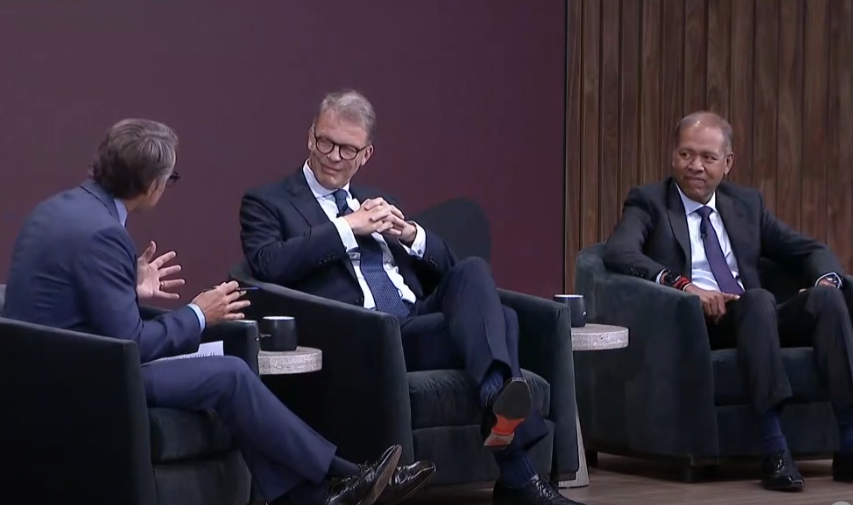
Perspectives from Global Banks
One could easily say the most notable announcement at the 1st Canada Investment Summit in Toronto last week was the Canadian government’s goal of catalyzing $1 trillion CAD in investment over the next five years.
In the final panel conversation of the day, entitled “ A Global Perspective: Financing Canada’s Future,” moderator Erik Schatzker opened the discussion between panel members Christian Sewing, Chief Executive Officer, Deutsche Bank AG and C.S. Venkatakrishnan, Group Chief Executive, Barclays PLC, with a reminder of the complex aspects of global investing.
“One thing we all know about capital, something we’ve been talking about all day long … is that it is discriminating,” Schatzker said. “Investors here, and for that matter, everywhere apply a complex matrix of variables to gauge risk and returns and to allocate it accordingly. Where does Canada fit in that capital equation, and what will it take to optimize the outputs of that equation in Canada’s favour?”
Global Competition for Capital
It is true that the demand for capital globally is dominated by the multi-trillion-dollar data center build-up, multi-trillion-dollar global electricity grid upgrades, and the multi-trillion-dollar energy transition. In spite of the magnitude of this competition, capital deployment has been concentrated in certain sectors that are associated with AI – associated with data centers and clean energy. These are all areas in which Canada has great advantages.
“The second thing is that in Canada, you’ve got the expertise,” C.S. Venkatakrishnan, Group Chief Executive, Barclays PLC said. “… expertise to build the projects and to deploy the projects. You’ve got the expertise to understand how best to use capital, and not just with the tax policies announced today, you’ve got the right legal and incentive system to generate those returns”
Venkatakrishnan mentioned that for most countries in the world, a $1 trillion goal similar to Canada’s goal would be unrealistic as they lack the type of resources needed to execute. He acknowledged that there are things that Canada has to do to make it easier to attract investment. He referred to the need to solve “frictional issues” pertaining to planning and permitting and sees the task at hand as defining the projects, defining what expected returns are, thus making it easier for foreign and domestic investors.
Canada’s Advantages- Do they outweigh the Frictions?
Both panel members, Venkatakrishnan and Sewing, had praise for Canada’s advantages, including low debt-to-GDP ratios, strong legal frameworks, as well as expertise in key sectors. Sewing advised that Germany will host their own investment summit in four weeks’ time, and humorously said he had taken “many notes” to bring home to Germany’s summit. He said that in addition to capital, skills, and resources, Canada also has trust and values, as Mark Carney emphasized in his address. Geopolitical disturbances have increased in the past year, making global investors shift their focus to emphasizing democratic values, independent institutions and reliability or trust.
“I have talked to so many investors around the world over the last 12 to 18 months.” Sewing said. “… and seen the shift in their minds when it comes to independent institutions, (looking for) a legal framework, democratic values, reliability, and long-term planning. You have all that here. I do believe that this is massive growth. Secondly, investors want to diversify, and therefore I think Canada is far more important than ever before. Now I think what could stand in the way is that Canada is a little bit like Europe. So you are in a race with Europe.”
Sewing added that what Canada really needs to show over the next four months is delivery on the projects and delivery on the “One project, One review, One year promise”.
Satisfying the Capital Needs of Canada’s Projects
The panel acknowledged that domestic capital alone will not satisfy the capital needs of Canada’s projects. Schatzker pointed out that both speakers sit at the nexus of global capital flows. In his words, both speakers know “who has the money, who needs the money”, and they “ know the price”. He noted that price is an important variable. The cost of long-duration capital is rising. Yield on the 10-year U.S. Treasury topped 5% on September 14th, and was holding above 5% on September 15th. He noted that U.S. Treasury Secretary Scott Bessent commented that AI developers’ borrowing binge is pushing up rates, perhaps even crowding out the U.S. government in the bond market. Schatzker asked the panellists, “What happens to the kinds of infrastructure projects that Canada wants to finance if these 10-year yields, or any yield, for that matter, keep climbing. Do they have to reprice to compete for global capital? And if they can’t reprice, does that make them unfinanceable?”
Venkatakrishnan credited persistent inflation across the world, rising debt-to-GDP ratios, and the supply of debt coming in, especially from the data center buildup, for the increases in the price of capital. He advised that persistent inflation and rising debt-to-GDP ratios apply less in Canada than in other countries.
Sewing agreed with Venkatakrishnan, but said we all need to take into consideration that, in his view, credit across the world will reprice and will get more expensive.
“So I do believe we will face a situation globally that credit capacity will cost more money,” Sewing said. “… and that actually means that the delivery of the project, the pricing of the project, the accuracy, the discipline to deliver, is getting more and more important. That brings me to my first point: you need to implement (measures) now. And if you can show that, then you have all the advantages. And then I think the repricing will hit Canada less than most other regions in this world.”
Equity participation & Debt financing – Where do global banks fit in?
Many of the conversations at the summit were about equity and equity participation in projects that Canada wants. Debt financing is key for banks -the banking system is vital to finance capex, and that requires accuracy in delivery times.
“Why is Canada actually a very attractive region?” Sewing asked. “Number one, you have the resources. Number two, from a diversification point of view, for a European bank, we don’t actually have so much Canadian exposure. For the next five to 10 years, that exposure is even more important for Europe. The banking system is vital to finance that capex. Here you have bigger and deeper capital markets.”
Venkatakrishnan advised that the reason Barclays is at the Summit was that they are intermediaries in the capital markets. Barclays connects sources of capital, debt capital, or equity capital, to sources of investment, and Canada brings advantages to connect to them. Barclays can participate or partner with Canadian institutions which have Canadian dollar financing and access to cheaper deposits. A partnership that makes the cost of financing cheapest is key.
Does the Canadian government have a role to play?
But how much of a role does the Canadian government need to play to make the cost of financing more attractive, or the returns more attractive to investors? (Whether it’s in the form of tax incentives, loan guarantees, or offtake agreements)
There was some agreement on the panel that the best approach is to rely on the private market as much as you can- hence the tax policies that have been announced.
The issue of implementation continues to be important for the Canadian government to address effectively- to make the regulatory planning/permitting process work (for example, by reducing duplicative provincial/federal IAA assessment processes) and to reduce what the panellists termed as “the frictions” that delay or obstruct delivery and to improve tax frameworks to make projects “investable”.
Perhaps the ability to execute is the greatest hurdle that Canada faces.
Maureen McCall is an energy professional who writes on issues affecting the energy industry.
Share This: