


 CDN NEWS |
 US NEWS


By Tegan Hill and Jason Clemens
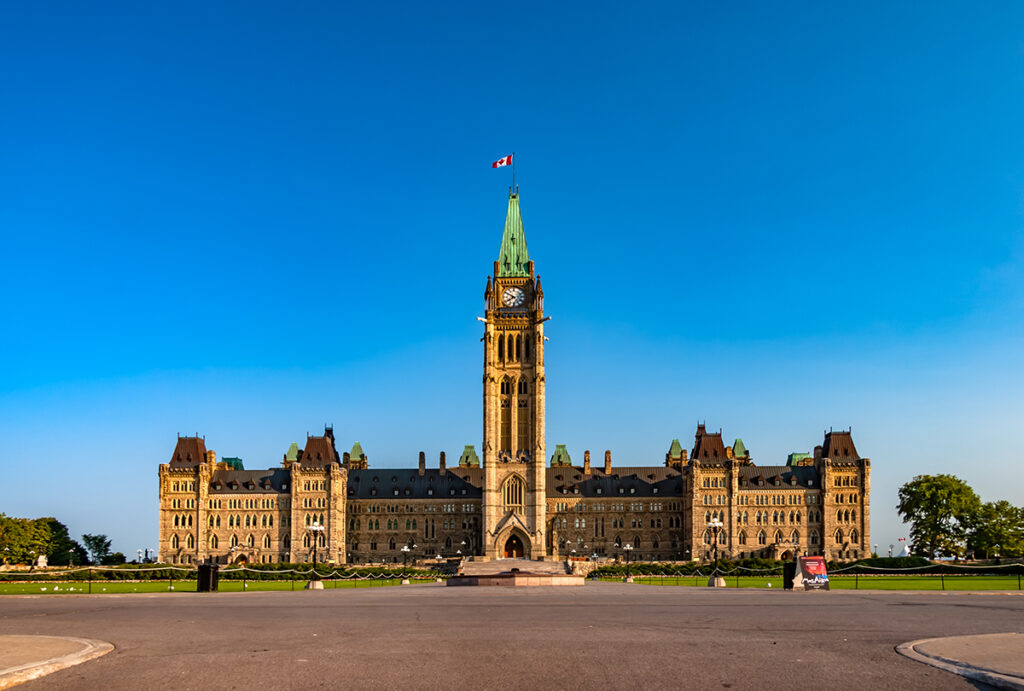
Nobel laureate Milton Friedman warned there’s “nothing so permanent as a temporary government program.” The Carney government’s Bill C-39, a massive bill of almost 250 pages, takes a power provided temporarily to cabinet in 2025 and makes it permanent.
One of the Carney government’s first legislative initiatives post-2025 election was Bill C-5, the One Canadian Economy Act. Among many measures, Bill C-5 provided the federal cabinet, which effectively means the prime minister, discretionary power to exempt certain projects from existing laws and regulations if the project was deemed to be in the “national interest.”
There were reports at the time that senators openly called the bill the “trust me” act because it lacked guardrails and details including the vagueness of defining “national interest.” It essentially meant that parliamentarians were trusting that the prime minister and cabinet would use the new discretionary powers reasonably.
To be clear, if Canada is to be a country of laws, such laws must apply to all citizens. Canadians should have been more reluctant to grant discretionary power to politicians to circumvent their own laws and regulations when they deemed it reasonable.
To deflect from some of that criticism, the bill included a sunset clause after five years, meaning the powers granted to cabinet would be terminated unless renewed via legislation in Parliament. The sunset clause aligned with the rationale that Canada was facing an existential threat from the actions of the U.S. president and needed to act expeditiously to attract business investment and build infrastructure to enable the country to diversify its exports.
There’s no doubt Canada has and continues to face a business investment crisis. Over roughly the last 10 years, there’s been a massive flight of capital from Canada with business investment plummeting. For perspective, from 2014 to 2024 (the latest year of available data), business investment per worker in Canada declined by 18.8 per cent—from $20,310 to $16,493—yet increased by 31.3 per cent—from $23,263 to $30,555—in the United States (adjusted for inflation, in Canadian dollars).
Canada’s current investment crisis is linked to a slew of laws and regulations introduced under the Trudeau government. The long list includes Bill C-69—which imposes onerous, uncertain and subjective review requirements for major projects—Bill C-48, which effectively bans oil tankers from Canadian ports on the west coast (but does not affect tankers travelling from Alaska to the U.S. mainland), and a costly industrial carbon tax that drives up Canada’s power prices and makes major energy projects woefully uncompetitive with other jurisdictions including the U.S., among other policies.
Now, the federal government’s Bill C-39, the Building Canada Strong Act, purports to “bring greater speed, certainty, and predictability to infrastructure project reviews.” But one aspect of the bill is that it makes permanent the extraordinary discretionary powers granted to cabinet to pick winners and losers via Bill C-5, while continuing to avoid the harder work of actually fixing the various regulations impeding business investment. And crucially, the definition of “national interest” continues to be subjective and ambiguous. In fact, in practical terms it can be any factor the cabinet deems fit, rather than based on a clear test or criteria.
All businesses, entrepreneurs and potential investors face these existing regulations and laws that have resulted in Canada becoming known as a place where you can’t get things done. Only companies whose projects are deemed to be in the “national interest” by a handful of politicians are granted the ability to circumvent the existing problematic laws and regulations. This troubles all Canadians since it means there is one set of laws and regulations for most people but a different set of rules for those favoured by cabinet.
It’s hard to see how such politicized exemptions and the further concentration of economic power in the prime minister’s office will improve the economic and business investment environment for the whole country. Indeed, it’s more likely that such actions continue Canada on a path towards corporate cronyism where economic activity is driven largely by political rather than economic decisions.
Rather than fixing the problematic regulatory processes, the Carney government is granting cabinet (again, effectively the prime minister) permanent power on major economic decision-making through Bill C-39. Not only does this put immense power in the hands of a few politicians, it actually increases uncertainty and likely continues Canada’s investment crisis.
Share This:
COMMENTARY: Newfoundland Government Should Use Hydroelectric Deal to Help Repair its Finances